By Amy Green
Buying a luxury home along the North County coast often means stepping beyond conventional loan limits, and that’s where jumbo financing comes in. In San Diego County, many homes in Encinitas, Carlsbad, Solana Beach, and Del Mar are priced well above the conforming limit, so understanding your options early is one of the smartest moves you can make. Jumbo loans offer flexibility for buyers who are well prepared, and the process is far easier when you know what lenders look for. Here’s a clear guide to financing your coastal luxury home.
Key Takeaways
- The 2026 conforming loan limit in San Diego County is $1,104,000 for a one-unit home.
- Loans above that amount are considered jumbo loans.
- Jumbo lenders typically look closely at credit, reserves, and documentation.
- Getting pre-approved early strengthens your position in competitive coastal markets.
What Is a Jumbo Loan in San Diego County?
A jumbo loan is a mortgage that exceeds the conforming loan limit set each year by the Federal Housing Finance Agency. For 2026, the FHFA set a baseline limit of $832,750 and a ceiling of $1,249,125 for high-cost areas, and San Diego County’s one-unit limit is $1,104,000.
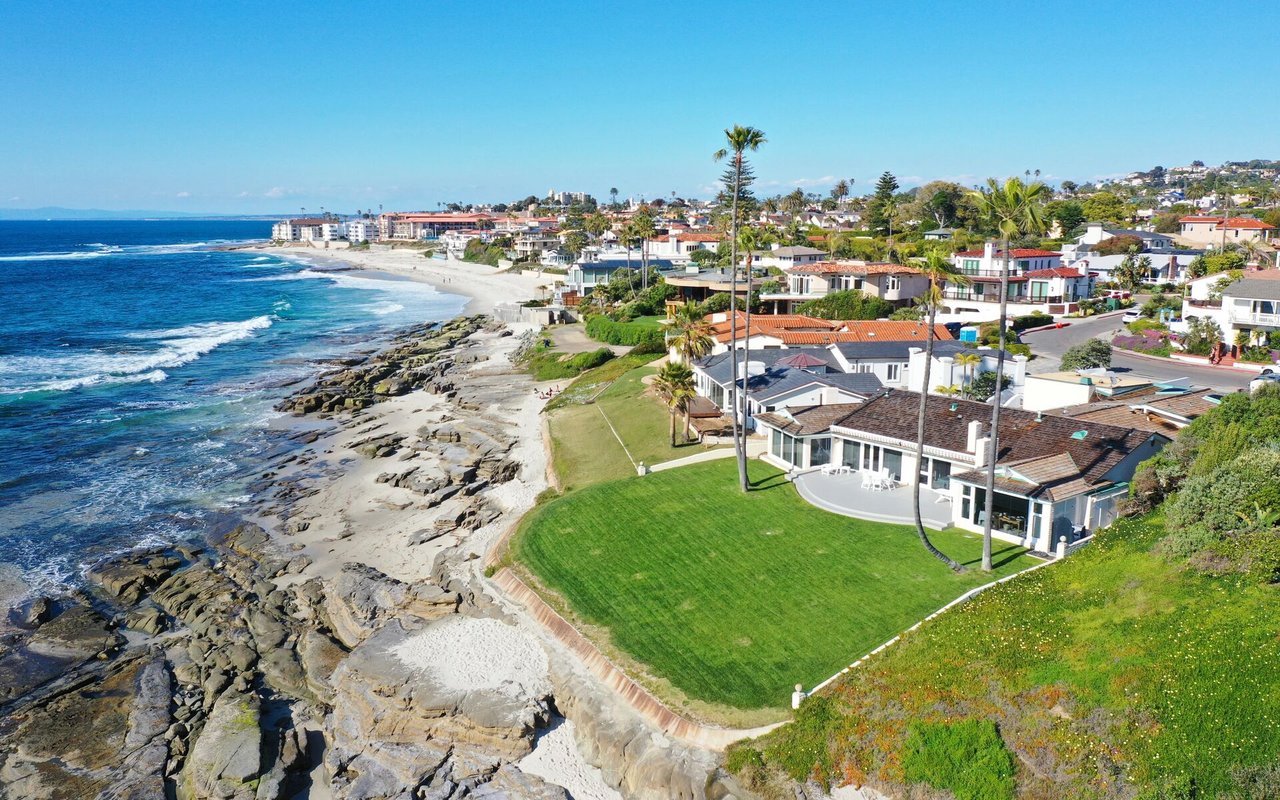
Because many coastal homes in North County exceed that amount, jumbo financing is a common part of luxury purchases here, whether you’re buying near the beach in Leucadia or in the hills of La Costa.
How Conforming Limits Affect Your Purchase
- Loans at or below $1,104,000 in San Diego County can typically be financed as conforming loans.
- Loans above that amount generally require jumbo financing, which often comes with different qualifying guidelines.
- Conforming limits are updated annually, with the FHFA announcing the 2027 limits in late November 2026.
- Your loan amount, not your purchase price, determines whether a loan is jumbo, so a larger down payment can change the picture.
How Do You Qualify for a Jumbo Loan?
Qualifying for a jumbo loan usually involves stronger financial documentation than a conforming loan, because the lender is taking on a larger loan. Lenders often look for solid credit, a manageable debt-to-income ratio, and cash reserves after closing.
Requirements vary by lender, so comparing options with an experienced mortgage professional is worthwhile. Gathering tax returns, bank statements, and investment account records ahead of time keeps the approval process moving smoothly.
What Lenders Commonly Review
- Lenders review credit history and scores to assess your borrowing track record.
- Many jumbo lenders expect a larger down payment than conforming loans require.
- Cash reserves, often measured in months of mortgage payments, need to remain available after closing.
- Income and asset documentation may be more detailed for self-employed buyers or those with complex finances.
What Financing Strategies Work for Coastal Luxury Buyers?
The best financing strategy depends on your goals, timeline, and financial picture, and luxury buyers in North County often have several options. Some choose a traditional fixed-rate jumbo loan, while others explore adjustable-rate or combination structures.
Working with a lender who understands the coastal San Diego market helps you choose the right fit.
Options Worth Discussing With Your Lender
- Fixed-rate jumbo loans offer predictable payments for buyers planning to stay long term.
- Adjustable-rate jumbo loans may offer lower initial rates for buyers who expect to move or refinance in a few years.
- A combination of a first mortgage at or below the conforming limit and a second loan can sometimes reduce the jumbo portion.
- Buyers with significant assets may explore asset-based or portfolio loan programs offered by some banks.
Frequently Asked Questions
Are jumbo loan rates higher than conforming rates?
Not always, since jumbo rates depend on the lender, market conditions, and your financial profile. Comparing quotes from several lenders helps you find competitive terms.
How much should I put down on a jumbo loan?
Down payment requirements vary by lender and program. A larger down payment can strengthen your application and, in some cases, keep your loan within conforming limits.
When should I get pre-approved for a jumbo loan?
It’s best to get pre-approved before you start touring homes, since jumbo approvals can take additional documentation. A strong pre-approval also makes your offer more competitive and gives sellers confidence that your financing is on solid footing.
Contact Amy Green Today
Financing a luxury coastal home is easier when you understand your options and have the right team in place. I’d love to help you connect with trusted lenders and find a home in Encinitas, Carlsbad, or anywhere along the coastal San Diego shoreline.
If you’re planning a luxury purchase in North County, reach out to me, Amy Green, and let’s talk about your next step.